What is blockchain? In simple terms, blockchain is a shared digital record book that many computers keep at the same time. Instead of one company controlling the record, copies are spread across a network. When a new entry is added, the network checks it, links it to earlier entries, and stores it in a way that is difficult to change quietly. That shared design is why people describe blockchain as transparent and hard to tamper with, although it is not perfect and it is not suitable for every problem.
This beginner guide explains blockchain without jargon, hype, or investment promises. You will learn how blocks and chains work, what decentralisation means, where blockchain is used, where it is not useful, and what to check before trusting a blockchain project. The goal is understanding, not a recommendation to buy anything.
A simple way to picture blockchain
Imagine a notebook shared by a whole class. Each page records a set of transactions, such as who sent something to whom. Once a page is full, it is sealed and a code from that page is written at the top of the next page. If someone tries to change an earlier page, the code will no longer match, and the class can see that something is wrong.
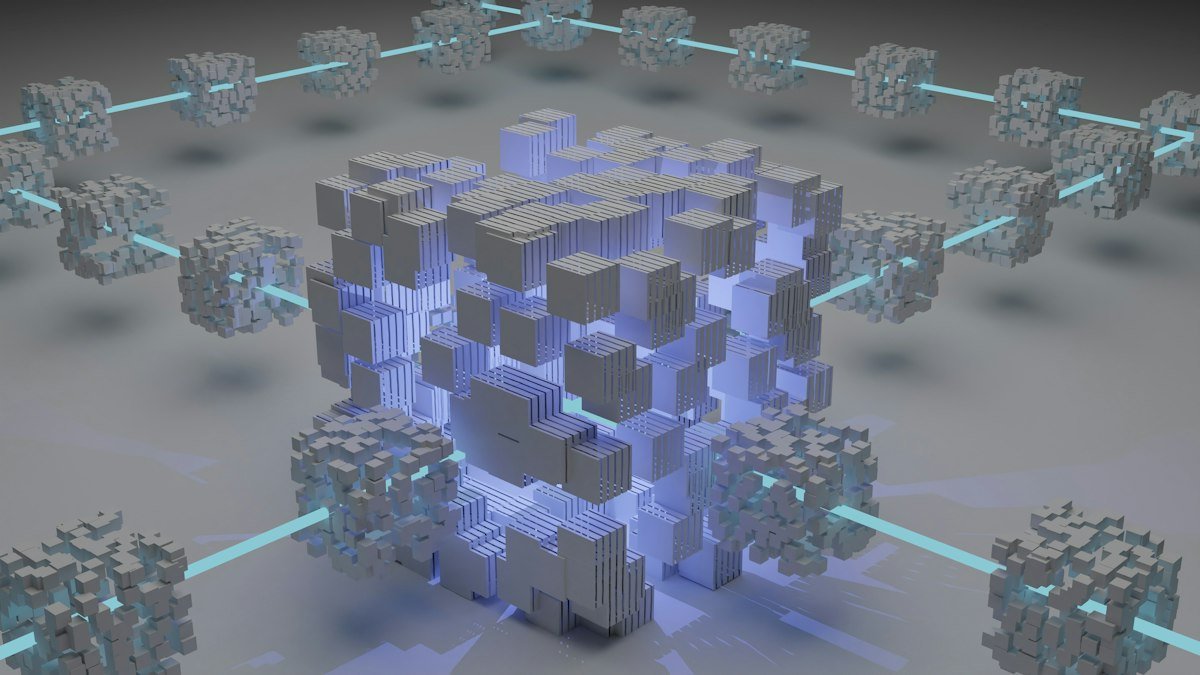
Blockchain works in a similar way. A block is a group of records. Each block contains a link to the previous block, usually through a cryptographic code called a hash. A hash is like a fingerprint for data: even a small change creates a completely different fingerprint. Because blocks are linked, changing one old record would require changing every later block too, which is difficult when many computers hold copies.
The network, not a single owner, maintains the record. Computers called nodes store copies and follow shared rules to agree on new entries. This agreement process is called consensus. Different blockchains use different consensus methods, and those methods affect speed, energy use, and security.
Key terms in plain English
Decentralisation means control is spread out rather than held by one central authority. A decentralised network can still have large players and uneven influence, so the word does not automatically mean fair or democratic. It simply describes how the system is organised.
A ledger is a record of transactions. In blockchain, the ledger is shared and updated across the network. A wallet is software that stores the keys needed to access and send digital assets. A private key is like a secret password that proves ownership. If you lose it, you may lose access permanently, depending on the system.
A smart contract is a programme stored on a blockchain that runs automatically when conditions are met. For example, it might release a payment after delivery is confirmed. Smart contracts can reduce manual steps, but they can also contain bugs. Once deployed, fixing them can be difficult, so they need careful testing and review.
How a blockchain transaction works
First, a user creates a transaction, such as sending a digital asset to another wallet. The transaction is broadcast to the network. Nodes check that it follows the rules, for example that the sender has enough balance and has signed it correctly. Valid transactions are grouped into a block.
Next, the network agrees to add the block. The exact method depends on the blockchain. Some networks use proof of work, where computers compete to solve a puzzle. Others use proof of stake, where validators are chosen partly based on assets they lock up as a stake. Once added, the block becomes part of the chain and is shared with other nodes.
Finally, the recipient can see the transaction in the shared record. Confirmation time varies. Some blockchains confirm in seconds, while others take minutes. Fees also vary with demand and network design. During busy periods, fees can rise sharply, which is one reason blockchain is not always cheaper than a traditional payment system.
Public, private, and permissioned blockchains
A public blockchain is open to anyone who wants to join, read records, or take part in validation under its rules. A private blockchain is controlled by one organisation, which decides who can join. A permissioned blockchain sits between these models: selected participants can read or validate, but access is restricted.
Public blockchains are useful when strangers need a shared record without trusting one central party. Private and permissioned blockchains can be faster and more private, but they rely more on the organisation running them. For many business uses, the choice is not simply public or private, but which trade-offs matter most: openness, speed, privacy, and control.
Where blockchain is actually used
Cryptocurrencies are the best-known use, but blockchain is also used in other areas. Supply chain systems use it to track products from factory to shop, helping companies check where goods came from. Some identity and document systems use it to verify certificates, licences, or academic records. Artists and creators use digital tokens to show ownership of digital work, although ownership of a token is not always the same as copyright ownership.
In finance, blockchain is used for cross-border payments, settlement, and tokenised assets. These systems can reduce some middlemen, but they still need regulation, customer protection, and reliable links to real-world assets. In healthcare and government, pilot projects test secure record sharing, but privacy rules and legacy systems make adoption slower and more complex.
Not every database needs blockchain. If one trusted organisation already keeps accurate records, a normal database is usually simpler, faster, and cheaper. Blockchain adds value mainly when multiple parties who do not fully trust each other need a shared, tamper-resistant record.
Benefits and limits, honestly explained
Blockchain can improve transparency because records are shared and difficult to alter. It can reduce reliance on a single intermediary and create a clear audit trail. In some cases, automation through smart contracts can speed up routine steps and reduce paperwork.
But blockchain also has limits. It can be slow and expensive compared with traditional databases. Energy use varies widely by design, and some older systems use a great deal of electricity. Data stored on a public blockchain may be visible to others, which raises privacy questions. Errors in a smart contract or a lost private key can be hard to reverse. And blockchain does not guarantee that the original data was true: if false information is entered, the chain will faithfully preserve a false record.
Security also depends on implementation. A blockchain is only as strong as its software, its network size, and its users’ habits. Phishing, fake apps, and poor key storage cause many losses, even when the underlying chain works as designed.
Blockchain and cryptocurrency are not the same
Many beginners confuse blockchain with cryptocurrency. Blockchain is the underlying technology. Cryptocurrency is one application of it. You can understand and use blockchain ideas, such as shared records and digital signatures, without buying or trading crypto assets.
Crypto prices are volatile, and markets can fall sharply. This guide makes no investment advice and no promise of returns. Anyone considering crypto should research independently, understand the risks, check local regulations, and never invest money they cannot afford to lose. Be especially careful with projects that promise guaranteed profits, pressure you to act quickly, or ask you to share private keys.
How to judge a blockchain project
Start with the problem. What does blockchain solve here that a normal database cannot? If the answer is vague, that is a warning sign. Next, check who runs the project, whether the code is reviewed, and whether independent audits exist. Look for clear documentation, realistic roadmaps, and honest discussion of limits.
Also check governance: who can change the rules, and how are decisions made? A project that claims to be decentralised but is controlled by a few people may not match its marketing. Finally, check regulation and user protection. Is the service licensed where required? What happens if something goes wrong? If these answers are hard to find, proceed with caution.
Frequently asked questions
Is blockchain the same as Bitcoin?
No. Bitcoin is a cryptocurrency that uses blockchain. Blockchain is the broader technology that can support many different systems, including but not limited to cryptocurrencies.
Can blockchain records be changed?
Changing a well-established public blockchain is very difficult because many copies would need to change. However, records are not absolutely unchangeable, and private blockchains can be changed by their operators under their own rules.
Is blockchain safe?
Blockchain can be secure when designed and used well, but safety also depends on software quality, key storage, and user behaviour. Scams and mistakes remain common risks.
Do I need blockchain for my small business?
Usually not. Most small businesses do fine with a normal database, accounting software, and trusted payment providers. Blockchain is worth considering only when a shared, tamper-resistant record across multiple parties is genuinely needed.
For related guides, explore Virtual Reality in 2026 and What Is the Internet of Things?, or browse the Trending Tech News category and the AliDigitalTech homepage.
What is blockchain, in short? It is a shared, linked record system maintained by a network rather than a single owner. It can bring transparency and a clear audit trail, but it is not a cure-all. Understanding its strengths, limits, and risks helps beginners judge new projects calmly, without hype or fear.
Pingback: How Does the Internet Work? A Simple Beginner Guide - AliDigitalTech
Pingback: Referral Apps Explained: How They Work and What to Check